
Payroll Internal Controls Checklist for Businesses
Last updated:
PayrollOrg’s 2025 survey found that 38% of organizations do not track payroll performance, showing that payroll oversight remains a challenge for many businesses. Effective payroll internal controls help reduce this exposure by strengthening how employee data, payroll calculations, approvals, payments, and reconciliations are reviewed. This payroll internal controls checklist covers the key controls businesses need to prevent errors, unauthorized changes, and fraudulent payments.
Where Do Payroll Fraud and Errors Typically Occur?
Payroll fraud and errors usually occur where sensitive data, approvals, and payments change hands. The risk is not limited to payroll calculation itself; it can begin when an employee record is created, continue through time and salary inputs, and remain undetected until funds are released or the payroll is reconciled.
This risk can persist across multiple payroll cycles when control weaknesses remain undetected. According to ACFE’s 2026 Report to the Nations, payroll fraud schemes had a median duration of 13 months before detection, with a median loss of approximately $4,800 per month. This makes early preventive and detective controls important before recurring errors or manipulation become embedded in routine payroll processing.
The most common risk points include:
- Ghost or terminated employees: Fictitious workers are added to payroll, or former employees remain active after leaving.
- Unauthorized master-data changes: Bank accounts, salary rates, tax details, deductions, or employment status are changed without proper approval.
- Timesheet and payroll adjustment fraud: Inflated hours, unauthorized overtime, unsupported bonuses, commissions, or off-cycle adjustments increase payroll costs.
- Weak payroll access: Excessive permissions allow unauthorized users to view or modify payroll data.
- Bank-file tampering: Beneficiary details, account numbers, or payment amounts are changed after payroll approval but before payment release.
- Duplicate or incorrect payments: Repeated payroll runs or poorly controlled adjustments create overpayments that are not detected promptly.
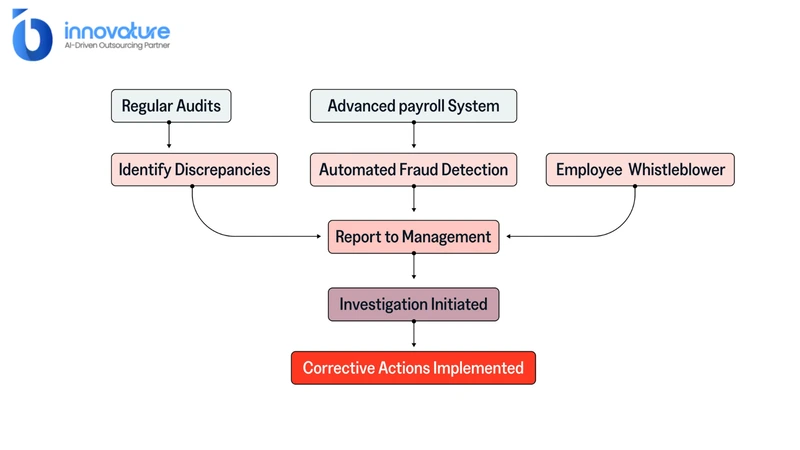
These risks occur at different stages of the payroll cycle. Each therefore requires a specific preventive or detective payroll control, rather than relying on one final review before payment.
Payroll Internal Controls Checklist
An effective payroll internal controls checklist should combine three elements: controls that prevent errors before payroll is processed, controls that detect unusual activity, and clear evidence showing who reviewed and approved each step. Together, these controls help protect payroll from employee setup through payment and reconciliation.
| Stage & Payroll Risk | Key Internal Control | Control Owner | Frequency | Verifiable Audit Evidence |
|---|---|---|---|---|
| Stage 1: Pre-Payroll | ||||
| Ghost / Fictitious Employees | Match active payroll roster against official HR hiring authorizations and contracts. | HR Operations | Every Payroll Run | Approved HR onboarding tickets, Signed employment agreements |
| Terminated Employees Still Paid | Cross-check termination logs against payroll cut-off lists to deactivate profiles immediately. | HR Operations | Every Payroll Run | Offboarding sign-offs, System deactivation timestamps |
| Unauthorized Bank Account Changes | Enforce secondary out-of-band verification (e.g., callback or dual-signed document) before updating bank details. | HR / Payroll Admin | Per Occurrence | Completed change request form, Confirmation email/call log, System audit log |
| Unauthorized Base Pay / Status Changes | Restrict pay rate updates strictly to signed authorization from HR/Senior Management. | HR / Compensation | Per Occurrence | Signed compensation review letters, Board/Director approvals |
| Stage 2: Payroll Processing | ||||
| Inflated Hours / Fictitious Overtime | Require primary Line Manager digital approval on all timesheets, overtime, and shift differentials prior to cut-off. | Line Managers | Every Payroll Run | Signed/digital timesheet approvals, Biometric punch logs |
| Unauthorized Variable Adjustments | Require formal Finance/Department Head pre-approval for bonuses, commissions, retro-pay, and deductions. | Finance / Dept Head | Every Payroll Run | Written incentive approvals, Supporting calculation schedules |
| Calculation & Input Errors | Segregate duties: Payroll Specialist calculates the gross-to-net register (Maker); Payroll Lead/Manager validates formulas, tax brackets, and totals (Checker). | Payroll Lead / Reviewer | Every Payroll Run | Maker-Checker sign-off sheet, Pre-final payroll register review notes |
| Excessive System Privileges | Review user roles in the HRIS/Payroll system; enforce Principle of Least Privilege and MFA for administrative tiers. | IT Security / Finance Lead | Quarterly | User access matrix reports, Quarterly access recertification sign-offs |
| Stage 3: Payment Execution | ||||
| Bank File Tampering / Interception | Generate encrypted/read-only ACH or bank files directly from approved payroll software; restrict manual edits. | Payroll Specialist | Every Payroll Run | System-generated file checksum/hash, Audit export logs |
| Disbursement Discrepancy | Compare total payment value and beneficiary headcounts between the approved final register and the bank upload summary. | Treasury / Finance | Every Payroll Run | Bank batch confirmation report vs. Approved payroll summary match sheet |
| Single-Point Payment Release | Enforce dual-authorization on banking portals (one user uploads, a separate authorized officer releases funds). | Authorized Payment Approvers (CFO/Director) | Every Payroll Run | Bank portal authorization audit logs showing dual release |
| Stage 4: Post-Payroll & Reconciliation | ||||
| Unrecorded Variances & Cost Spikes | Perform period-over-period payroll variance analysis (MoM / Run-over-Run) investigating any material variance above threshold | Financial Controller / Finance | Monthly | Monthly payroll variance analysis report with documented explanations |
| General Ledger Misalignment | Reconcile total payroll journal entries against the General Ledger (GL) cash and liability accounts. | GL Accounting | Monthly | GL account reconciliations, Cleared payroll clearing account balances |
| Tax & Statutory Non-Compliance | Reconcile statutory withholdings (payroll tax, social insurance, pension) against third-party remittances and filings. | Tax / Finance Team | Monthly / Quarterly | Tax filing receipts, Government remittance confirmation slips |
| Historical Ledger Manipulation | Lock/close the payroll accounting period permanently after final sign-off; route subsequent corrections via off-cycle adjustments. | System Admin / Controller | Every Payroll Run | System lock status log, Off-cycle adjustment authorization forms |
Enforce Payroll Segregation of Duties and Maker-Checker Controls
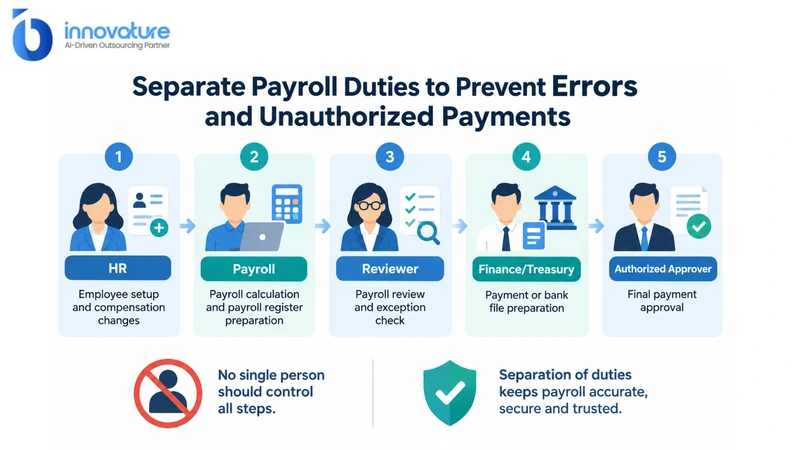
The basic rule of payroll segregation of duties is simple: no single employee should control the entire payroll process.
Responsibilities should be separated as follows:
- HR: Create and terminate employee records and authorize compensation changes.
- Payroll: Calculate payroll and prepare the payroll register.
- Reviewer: Check payroll results and investigate exceptions.
- Finance/Treasury: Prepare the payment or bank file.
- Authorized approver: Release the final payment.
This creates a clear Maker → Checker → Approver structure. The person who prepares or changes payroll data should not review the same transaction or approve the related payment.
For example, if one Payroll Specialist can create an employee, change bank details, and release payment, the same person could potentially create and pay a ghost employee without another person being involved.
This approach is consistent with the IIA Three Lines Model, which emphasizes clear responsibilities, management oversight, and independent review across business processes.
In an outsourced payroll model, these responsibilities may be shared between the client and a provider of finance and accounting outsourcing services, while final approval and control ownership remain clearly defined.
Control Employee Master-Data Changes
Employee master data includes more than bank details. It covers new hires, terminations, salary rates, tax information, benefits, deductions, and employment status. Within a payroll internal controls checklist, master-data controls are essential because these records directly determine who is paid, how much they receive, and where payments are sent. Because these fields directly affect payroll calculations and payments, every material change should follow a controlled process:
Request → Supporting evidence → Maker update → Independent approval → System log
Key controls include:
- Match new employees to approved HR records.
- Remove or deactivate terminated employees promptly.
- Independently verify bank-account changes.
- Require approved documentation for salary changes.
- Record who requested, entered, reviewed, and approved each change.
These steps reflect the authorization and documentation principles in the COSO Internal Control Framework, which emphasizes properly designed control activities and reliable information.
Approve Salary, Timesheet, and Payroll Adjustments
Payroll approval should cover three main types of input:
- Recurring inputs: Base salary and contractual pay rates.
- Variable inputs: Overtime, commission, allowances, and incentives.
- Exceptional inputs: Bonuses, severance, off-cycle payments, and retroactive adjustments.
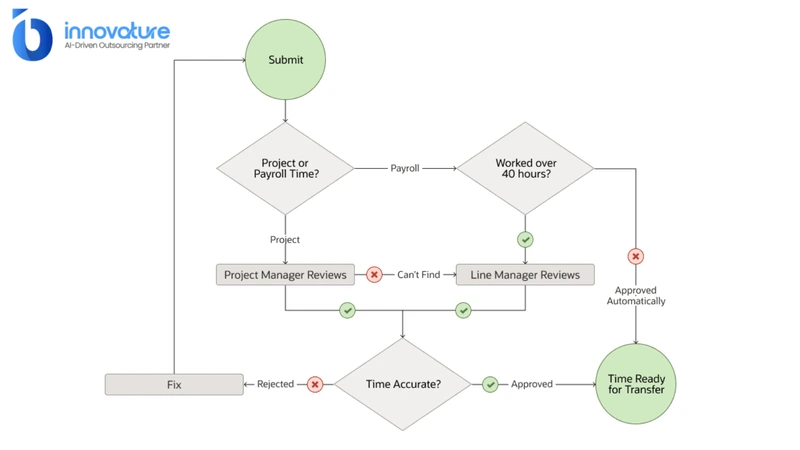
Line Managers should approve timesheets and overtime before payroll processing. HR or authorized management should approve salary changes, while Finance or another designated reviewer should check material payroll adjustments.
The person entering an adjustment should not approve that same item.
This control is especially important for variable pay. ACFE’s 2026 analysis of overtime fraud highlights inflated working hours and false pay rates as examples of how payroll fraud can be introduced through normal payroll inputs.
Restrict Payroll System Access
Payroll systems contain sensitive employee and payment data, so users should only receive the access required for their role.
Important payroll access controls include:
- Use role-based access control (RBAC).
- Apply least-privilege access.
- Require MFA for privileged accounts.
- Review user permissions regularly.
- Remove access promptly after termination or role changes.
- Monitor administrator and other high-privilege accounts.
For example, a payroll processor may need permission to edit payroll inputs, but that does not mean the same person should be able to change user permissions or approve bank payments.
The security risk is significant. The 2026 Ponemon Cost of Insider Risks study reported an average cost of about $842,462 per credential-theft incident. While this is not a payroll-specific study, it shows why sensitive payroll systems need stronger authentication and privileged-access controls.
NIST SP 800-53 also identifies access control, least privilege, and audit accountability as core security practices.
Control Bank-File Creation and Payment Approval
Payroll approval does not end the control process. The payment stage should follow a clear sequence:
Approved payroll → Bank file generated → Independent check → Upload → Authorized approval → Payment
Key controls include:
- Keep the bank-file creator separate from the final payment approver.
- Compare total payment value and beneficiary count with the approved payroll register.
- Restrict uncontrolled manual edits to payment files.
- Use secure file-transfer methods.
- Apply dual authorization where supported by the bank.
- Reconcile the final bank output with approved payroll data.

Payment fraud remains a broader business risk. The 2025 AFP Payments Fraud and Control Survey found that 79% of respondents reported their organizations experienced attempted or actual payments fraud in 2024. This reinforces the need for an independent control layer between payroll approval and final payment.
Perform Payroll Reconciliations and Variance Reviews
Reconciliation is one of the main detective payroll audit controls. It should compare payroll information across several sources, not only against the General Ledger. A complete payroll internal controls checklist should therefore require reconciliation across employee records, payroll results, bank payments, and accounting data.
Finance should review:
- Payroll register vs. approved employee list: Detect ghost or terminated employees.
- Current payroll vs. prior period: Identify unusual changes in headcount, salary, overtime, or total payroll cost.
- Payroll register vs. bank payment: Detect differences in beneficiaries or payment amounts.
- Payroll journal vs. General Ledger: Confirm complete and accurate accounting.
- Payroll liabilities vs. tax and benefit payments: Confirm obligations are properly recorded and settled.
Material differences should be investigated based on the company’s payroll size, normal volatility, and financial materiality, with significant exceptions carried into the broader accounting review before financial reporting.
This structured review is important because payroll monitoring is still inconsistent across organizations. PayrollOrg’s 2025 Getting the World Paid Survey found that 38% of organizations did not track payroll performance, while 26% relied on spreadsheets, BI tools, or manual reporting.
Maintain a Complete Payroll Audit Trail
A payroll audit trail should allow Finance or auditors to trace every material change. At minimum, the system should show:
- Who made the change.
- What was changed.
- When the change occurred.
- The old and new values.
- Who approved the change.
Audit logs should cover employee creation, salary changes, bank-detail updates, payroll adjustments, access changes, and payment approvals.
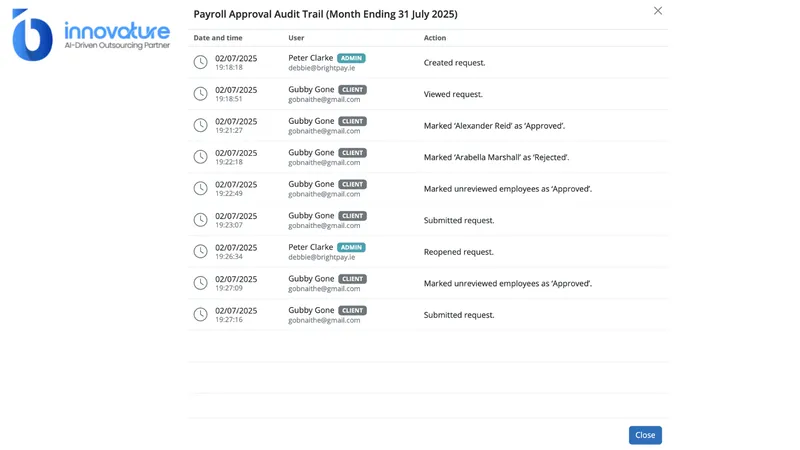
Once payroll is finalized, the period should be locked or restricted. Any later correction should go through a controlled adjustment process instead of overwriting historical records. Similar approval, documentation, reconciliation, and period-lock practices are also important within broader month-end close controls before financial results are finalized. Supporting documents should also be retained according to company policy and applicable legal requirements.
This approach is consistent with NIST’s Audit and Accountability controls and COSO’s focus on reliable information and ongoing monitoring.
Quick Payroll Control Health Check (Maturity Assessment)
Use this quick scorecard to evaluate the operational maturity of your organization’s payroll controls and identify immediate vulnerabilities.
| Evaluation Area | Red Flag (High Risk) | Green Flag (Mature Control) |
|---|---|---|
| Segregation of Duties | One person can update bank details and also authorize payment batches. | HR data entry, payroll register generation, and bank release are handled by separate individuals. |
| Master Data Maintenance | Bank account numbers or pay rates are modified based on unverified email requests. | Strict dual-authorization and verbal/callback verification exist for every master-data edit. |
| Banking & Payment | Text/CSV payment files are manually downloaded, adjusted in Excel, and uploaded to the bank portal. | Payment files are system-locked, auto-transmitted, or verified against register totals using dual-token approval. |
| Reconciliation Discipline | Reconciliations happen only at fiscal year-end or are limited to high-level GL balance checks. | Headcount, variance analysis, and cash-to-register clearing happen every single payroll run. |
| Audit Log Integrity | Historical payroll periods remain unlocked, or system changes lack user-stamped audit trails. | Closed periods are permanently locked; all master-data and pay-rate changes are fully traceable. |
If your operations display 2 or more Red Flags, immediate remediation is recommended to segregate duties, restrict manual spreadsheets, and formalize maker-checker controls.
This approach aligns with COSO’s emphasis on ongoing monitoring and evaluation of whether controls remain present and effective. ACFE’s 2026 Report to the Nations also found that organizations with anti-fraud controls experienced lower losses and faster fraud detection, reinforcing the value of regularly testing whether controls are actually working.
If your payroll process still relies on manual reviews, limited segregation of duties, or inconsistent reconciliation, additional operational support can help strengthen day-to-day controls. Innovature BPO supports Finance and Accounting teams with payroll processing, reconciliation, documentation, and structured review workflows while your internal team retains approval and control ownership.
Contact Innovature BPO to explore how an outsourced payroll support model can help improve control consistency, reduce processing risk, and support scalable payroll operations.

Finance leaders are under pressure to strengthen controls, close faster, improve data quality, and support business decisions without…

Vendor master data controls govern how supplier records are created, verified, approved, changed, and deactivated before they are…

Accounts receivable aging analysis helps finance teams evaluate unpaid customer invoices, identify overdue exposure, and decide which balances…
Finance outsourcing governance is a framework that defines roles, decision rights, internal controls, and provider oversight when finance…
Selecting a finance outsourcing provider does not make a finance process ready to move. Before operational ownership changes…
Payroll accuracy often breaks down before payment is even made. PayrollOrg’s 2025 global survey identified poor-quality input data,…
Intercompany balances become harder to control as businesses add legal entities, currencies, systems, and cross-border transactions. A single…

An accounting quality control checklist helps Controllers and Finance Managers verify whether bookkeeping data is accurate, supported, and…

Month-end close often becomes harder as growing companies process more invoices, payments, reconciliations, and reporting requirements. Without a…

Accounts payable journal entries record what a business owes suppliers and how those obligations change over time. A…

Financial statements analysis is the process of examining a company’s income statement, balance sheet, and cash flow statement…

An offshore accounting strategy defines which finance work should move offshore, how that work will be delivered, who…
Ready to move faster?
Trust us to find the best-fit candidates while you concentrate on building a skilled and diverse remote team.